
Markets continue to struggle badly, with most of European bourses down around 2% at the time of writing, largely on news from China, but not because of a further Crash in Shanghai (which closed up on the day) but because it should be clear to everyone now that China is now seriously in trouble on events somewhat at odds to the official Chinese government’s outlook.
We discussed on Monday (HERE) how the Chinese Manufacturing PMI, the most watched leading indicator, had been weak for some time, as the chart shows:

Source: Markit Click/Tap to Enlarge
Over this long time frame we can see easily how not only has it been below the 50 break-even level for more than twelve months, it has been struggling to recapture the post crisis highs for a while. This chimes with the falling figures on rail freight, container rates, shipping rates etc. Not to mention the collapse in the steel industry which has led to dumping the metal globally on a colossal scale.
However not to worry have said many, the Chinese government (you know, the chaps who magically produce GDP figures to within 0.1% of their – and therefore their acolytes in the big banks – targets every time….much more on this HERE) has told everyone how it is transitioning to a service economy, so it must be so. This is now the China story, ignore the tumbling freight volumes, Apps don’t need freight volumes…but then nor do they employee many people or generally add much value to, well I was going to say GDP, but more often than not, anything at all.
Of course the notion that an economy that has only just (over)industrialised and (over)built a modern infrastructure can suddenly transition to a mature service (and hence consumer) economy overnight is ludicrous beyond all comprehension, particularly as many of the “consumers” in this new economy are losing their jobs.
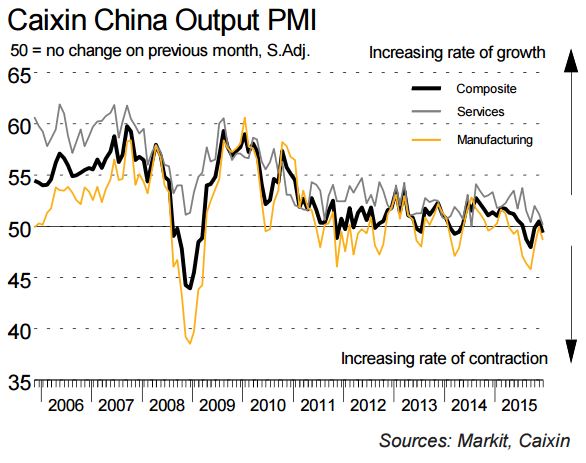
More to the point is that in this scenario the service PMI should be soaring, not coming in at 50.2, a rounding error above break-even, dragging the composite PMI into negative territory:
Source: Markit Click/Tap to Enlarge
The fact is that it will take China a decade or two (at best)to transition to a service economy and how that transition will interact with the rest of the global economy makes that narrative really rather complicated, however it is not the overnight story that some would like to believe in. Unfortunately in this day of instant everything the grasp of narrative flow, specifically the temporal element, has been lost by the “want it now” generation, who think that as soon as it occurs to them (usually long after more considered thinkers) it must happen “right now”. Regrettably this trend involves too many in the markets and commentariat who should, frankly, know much better.
However a very clear narrative flow is throwing up more data pointing to a significant slowdown as the Chinese Yuan continues to be devalued, with the unofficial offshore rate forcing the pace:

Source: ZeroHedge Click/Tap to Enlarge
You might note the last time this chart took a sharp southward move was back in the summer of 2015, around the time the markets wobbled badly, after all it is true to say the Shanghai stock market has little import in global terms….The value of the Yuan on the other hand?……That’s a different matter!
The odd thing is Chinese bank lending figures (allegedly…they were Chinese government figures after all) went through the roof towards the end of 2015 and was taken as as sign that the Chinese government was successfully re-stimulating, however there is little sign this is feeding through to increased activity. However it is perfectly plausible that this lending splurge was simply an effort to shore up failing/insolvent businesses (of which there are many) in which case it wouldn’t feed through to growth, simply stop a fall.
It looks clear now that China has felt the need to enter the currency war, which so far is being won by Europe, which was the real worry back in August, and to be fair it is probably justified in doing so after the appreciation it suffered post GFC.
The thing is that this removes yet another argument that everything is right with the world, when frankly it clearly isn’t. As a result it is miners leading the falls, with Crude Oil finding new (recent) lows as Brent Crude fell below WTI again, breaching the $35 pb level.
Early last year it was clear the Corrosive Equilibrium, that had held the world together post GFC, had dissolved within its own contradictions and we witnessed asset markets diverge from their unified upward only path. However this looks increasingly like the early days of change as economies and markets come to terms with the new reality and reset accordingly.
If we are lucky it will not get any more volatile than regular occurrences of the current episode, although we should expect many similar periods of uncertainty in that case. However even in simpler times periods of significant economic transition rarely went smoothly, so the opportunity for things to flow a little (or a lot) out of control should not be underestimated.
Let’s remain very careful out there.