
The shock of being Trumped seems overwhelming but it perhaps shouldn’t, after all as we discussed last week (HERE) Hilary Clinton was deeply disliked by many in the US for very clear reasons, even if that isn’t appreciated much over on this side of the pond.
However the unfortunate collective myopia of the establishment commentariat was writ large by SKY News anchorman Dermot Murnaghan who was chatting to Ronald Reagan’s adopted son, Michael, last night and seemed incredulous that Trump should be so popular when America had (and I paraphrase) “Never been richer, employment has never been higher, times were good” and his interlocutor replied that indeed and he had just talked to a young man who was very happy his 401K (the US version of Self Invested Personal Pension) had flown up in value over last few years.
Frankly I couldn’t help thinking that they really, really didn’t get it, although to be fair they are not alone because neither has the rest of the establishment and the sympathetic media. So let’s look at the reality
America has never been richer?
Well yes on headline Gross Domestic Product the US closed 2015 with a GDP of around $18tn and, let’s face it even in these days of monetary madness a trillion is a big number. Indeed compare that to the GDP at the end of 2007, which was around $15tn. So despite the downturn in the year that followed the US has grown by $3tn, or by 20%, so surely America is richer?
Well not really because in order to keep the wheels of the US turning they’ve taken on some extra debt….And when I mean some, I mean lots……..And when I mean lots…Well…..Let’s just digest the figures.
Back in 2007 the US had a national debt of approximately $9tn, somewhat less than its GDP. Now that figure is closer to $19tn, which is more than its GDP. Let’s look at that escalation graphically from 1980:

Source: TradingEconomic.com Click/Tap to Enlarge
Put another way they’ve added nearly $9tn in debt to produce $3tn in output. Now I ask you, do you think you could borrow $9tn and produce such poor results…..You’d be pretty darn disappointed in yourself wouldn’t you?
Politicians? Not so much!
OK, so America is actually poorer (a lot) by measures that normal people use, but surely we keep seeing reports of record low unemployment so let’s look more closely at this myth, which is demonstrably both an epic lie and a key element of establishment self-deception.
The reality is clear if you look at the actual basic data published by the BLS (Bureau of Labour Statistics) which shows how the workforce participation rate has fallen over recent years, as we can see in the following chart from the brilliant US analysis site, Doug Short’s Adviser Perspectives (found HERE)

Source: Advisor Perspectives Click/Tap to Enlarge
Now the lazy Bull narrative that this falling participation rate is all about Baby Boomers retiring early……Sorry, you’re wrong Bulls! In truth many simply can’t afford to as the following chart, highlighting the increased participation of the older generations shows all too clearly:

Source: Advisor Perspectives Click/Tap to Enlarge
In a world of ZIRP and QE and with the safer investments that the older generation is supposed to invest in (and that their Annuity holds) providing no return as a result, many ordinary retirees can’t retire.
However this isn’t the most desperate part of the story if we look how participation among prime working ages has been falling as people give up looking for jobs (in the US give up for 4 weeks and you are officially out of the labor force!):

Source: Advisor Perspectives Click/Tap to Enlarge
Frankly the real rate of unemployment is arguably closer to 9%, before we even consider the measure of part-timers who want full time jobs, then we are probably flirting with the teens.
This of course also fuels lower wage growth (indeed most of the job growth that has occurred has clearly been in non-breadwinner lower paid jobs) and thus lower consumption, and lower growth. This relationship is shown clearly by the clearly angry Jeffrey Snyder at Alhambra Investment Partners (find the full post HERE):

Source: Alhambra Investment Partners Click/Tap to Enlarge
Finally on this topic the particularly sharp falls in participation among the lowest age group is partly reflected in increasing numbers in higher education, often taking degrees of limited worth and saddling them with debt in perpetuity as the following chart on student debt levels tells a clear story (and how that debt has increasingly been packaged up and is traded on markets, you know, like mortgages were, is another story altogether):

Source: Advisor Perspectives Click/Tap to Enlarge
(For more details on this situation see our post from March last year HERE and the two recent Advisor Perspectives Articles providing these graphs can be found HERE and HERE)
Also let’s briefly consider the rapidly failing edifice (even before a staunch critic was elected) that is Obamacare, which has fallen foul of a pretty basic accounting error while operating in an intrinsically corrupt and oligopolistic health care/insurance market. You see ignoring the fact that free markets don’t work very well in an industry with long standing patents, and rules introduced by Bush that allow price gouging even by generic drug producers, the basic insurance principal of Obamacare was by making a system with lower cost they could draw in more young, less well paid participants who had normally shunned expensive health insurance.
Now by adding in more premium payers who rarely make a claim they spread the load for the elderly, in just the same way that annuity’s only work if a number of those receiving their pension helpfully decide to drop off the twig earlier than statistically likely. However think about being a young American, full of student debt you can never repay, with poor job prospects and in good health. Are you going to take out health insurance just in case, especially when there is usually a $5000 excess before it starts paying out and there is either Medicare if you are poor or perhaps even helpfully bankruptcy (that will take care of your other debts) as an alternative?
No? Me either.
Hence the cost of Obamacare has skyrocketed as participation among the younger generations (whose job prospects have dimmed) and is simply not providing the solution needed, which of course is a root and branch reform of a health system that highlights the worst elements of capitalism.
Now these are pretty key points for the ordinary working man and women who has seen Globalisation not as a great boom, providing cheap TV’s and phones with many functions no rational being actually needs, but as a way of impoverishing them as good jobs have been exported. People who have little skin in the game of asset markets booming on QE and ZIRP (because they can’t afford to) and have not seen a house price boom in their Middle American towns, those that fill the “Fly Over” states between the wealthy East and West Coast.
Now this is a story that will run and run but the truth is unbridled free markets have come at a very real cost to many and to fail to understand these facts is to fail to see reality.
However finally let’s come back to markets and let’s look at the notion that everyone’s pension is growing? Well let’s reprise the clear analysis of equity valuations and, just as importantly, briefly consider the implications for everyone’s pensions as a result of extended QE and ZIRP.
We have discussed many time before the absurd levels of stock market valuations (such as HERE around BREXIT) however this chart from Hussman Funds (the excellent weekly posts can be found HERE) shows the overvaluation of the Median S&P stock more starkly than words ever can:
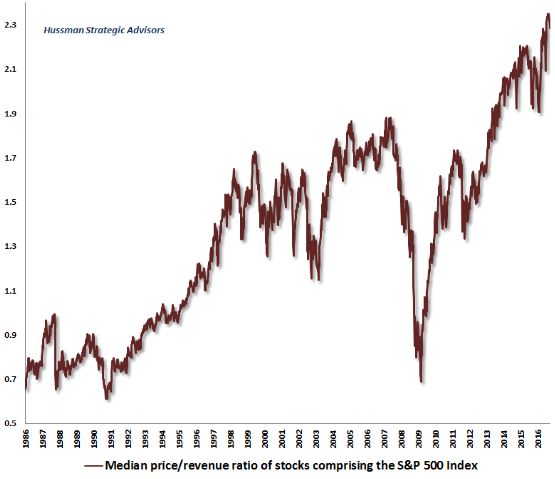
Source: Hussman Funds Click/Tap to Enlarge
But what does this mean, surely Central Banks can keep shares at these elevated levels forever?
Well there is so much so dangerously wrong with this notion on an intellectual and basic mathematical basis there are plenty of posts to come on the topic, however in simple terms when planning for the future shares or bonds produce a cash flow, which investor’s value against their needs and how much they are willing to pay for them (the technical term is calculating the Net Present Value, or NPV, of the assets and it’s key to ballooning pension fund issues).
The problem with permanently high asset prices, if not matched by the cash flows to support them (either through growing corporate earnings – not happening- or future interest payments – bloomin minimal, if at all) then an investor is only buying them to sell, hopefully at a higher price, to someone else who will pay even more for even less (the Greater Fool Theory).
More importantly analyzing the likely returns to the happy US 401K owner from his US Equity holdings it is likely to show, on a Total Return basis (so including income), more or less nothing for ten years utilizing any rational metric. That’s how overvalued US stocks are.
And of course that doesn’t mean they simply stay flat (or fall as the income is paid out) in a smooth fashion. No. Correcting this sort of over-valuation is usually a little more, ahem, exciting.
Hence the happy 401K owner should sell up PDQ if he wants to stay happy, although frankly this doesn’t mean we are seeing the start of a crash today, after all this was a “know unknown”.
Finally let’s face it when we look at establishment complacency remember Trump promises to “Drain the Swamp”….remove the stink of corruption and big business lobby money from Washington and the establishment who so clearly don’t understand much of the world they have created….on a fairly basic level.
That’s a very, very, very compelling promise to many, and frankly totally necessary if the US is to reinvent itself into the future and I remain an optimist for the US (and the UK) as despite all these clear difficulties the fundamentals are better than in many other places, especially China and Japan.
However just this one of Trump’s stated task is a big and complex one requiring much thought (so reason to worry already) so let’s see how he does “Drain the Swamp” when most of his new Republican colleagues are as up to their necks in the endemic corruption as Hilary.
Interesting times indeed.