
Unnoticed by the vast majority around Wednesday lunchtime on 23rd November the world got rather scary as financial markets went a touch haywire, a fact that went basically unreported by, well, anyone at the time.
Indeed rarely do things suddenly feel so odd with barely no-one commenting, and frankly the last time your correspondent felt things were going so awry was back in 2012, on the fateful day that Draghi felt impelled to extemporise his hopeful “whatever it takes” speech, although if you look backwards at the daily charts you will see nothing of interest there….you literally had to be in markets closely at the time….and honestly most journalists who commented on it at the seemed (and remain) blissfully unaware that there was the sense for a great unwinding going on beneath the surface.
Anyway back to the discombobulated present, the biggest market for financial instruments (as opposed to currencies – more anon) is the US Treasury market, hence a sharp rise in yields should be noticed. This is what happened during last week:

Source: MarketWatch Click/Tap to Enlarge
Frankly a move in the ten year yield of 6% in a couple of hours trading is very unusual in itself (even if it gave a bit back after equities opened) but large moves have been seen, such as in the Treasury Flash Crash of October 2014 (covered among other Flash Crashes HERE) however this was one of myriad events at the time.
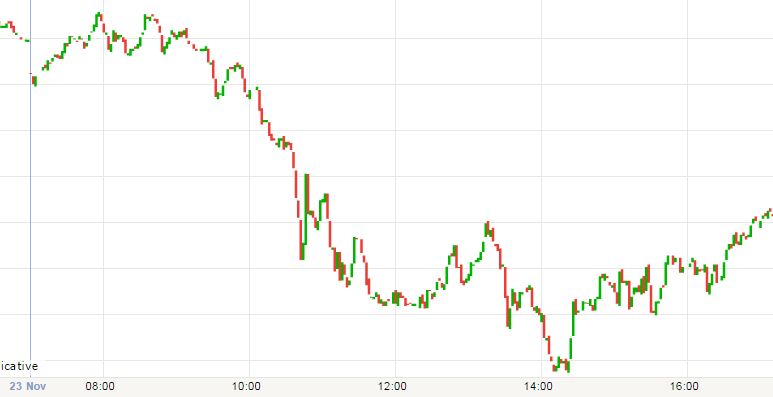
Concurrently we can see the French Government Bond market prices falling sharply (as its yield rose – hence the inverse direction compared to the Treasury above) until mid-afternoon.
Source: AG Click/Tap to Enlarge
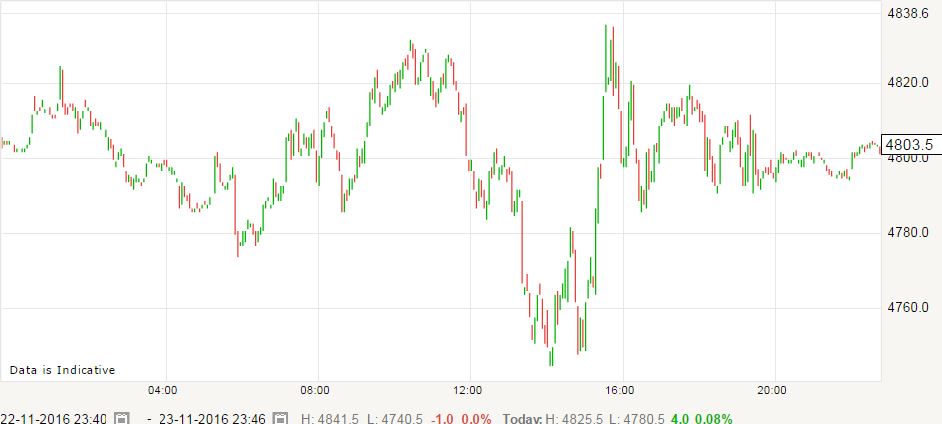
Next up we see the impact on Oil over the same time period, falling as yields rose (itself a contradictory message…rising yields equal rising inflation expectations, usually hand-in-hand with rising energy costs…..but discount causal rational relationships…..they only seem to work for the determinedly myopic at the moment). Interestingly the bounce back as US equities opened and rallied was equally notable:
Source: AG Click/Tap to Enlarge
While Gold also fell sharply, but deigned to rally:

Source: AG Click/Tap to Enlarge
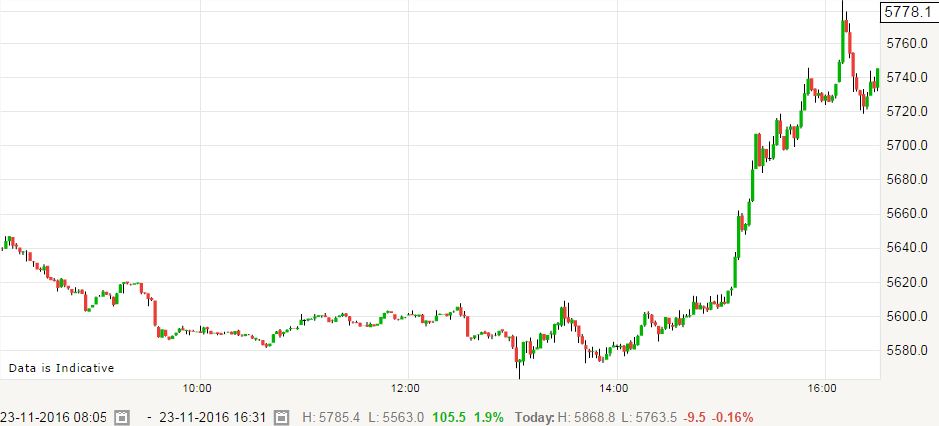
Although by contrast Copper had been doing nothing until the US Equity market opened positively and then rallied like billy-o!
Source: AG Click/Tap to Enlarge
Also falling prior to Wall Street yawning and deciding 9:30 was late enough to bother working were UK (and other European) equities:

Source: AG Click/Tap to Enlarge
All very odd, yet totally missed on the headlines (even the really dull ones we see) however, why should anything uncomfortable be reported by the media as the only thing that apparently matters are pesky US equities, which continued to ignore any semblance of rationality and simply plugged on up to ever more deranged valuations with zero volatility (naturally dragging in more MPT, CTA and Risk Parity money to possibly the most overvalued major equity market in history) as the S&P Chart shows:

Source: AG Click/Tap to Enlarge
You can see that while the market futures showed signs of weakness prior to the 14:30 (UK Time) opening it was barely a blip against other markets.
In the meantime the Dollar continued its sharp march up against the Chinese Yuan, spiking sharply on the 23rd:

Source: TradingEconomics.com Click/Tap to Enlarge
Which as a reminder is a continuation of the ongoing Dollar strength/Yuan weakness:

Source: TradingEconomics.com Click/Tap to Enlarge
While the Yen has also begun to fall back against the dollar, but again moved very sharply on the 23rd:

Source: TradingEconomics.com Click/Tap to Enlarge
This is a welcome return to trend for the Japanese whose unexpected negative rate policy at the start of the year backfired spectacularly as the Yen rallied in response and only now is slipping necessarily against the Greenback:

Source: TradingEconomics.com Click/Tap to Enlarge
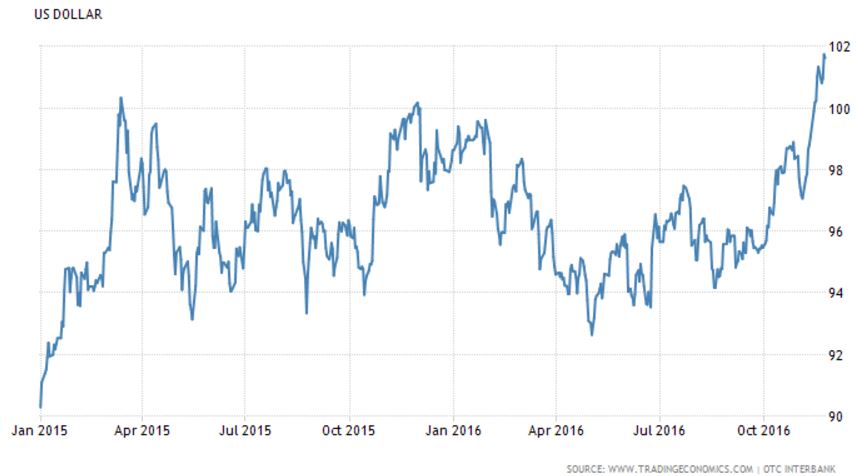
Concurrently the dollar accelerated against the basket of global currencies (DXY):
Source: TradingEconomics.com Click/Tap to Enlarge
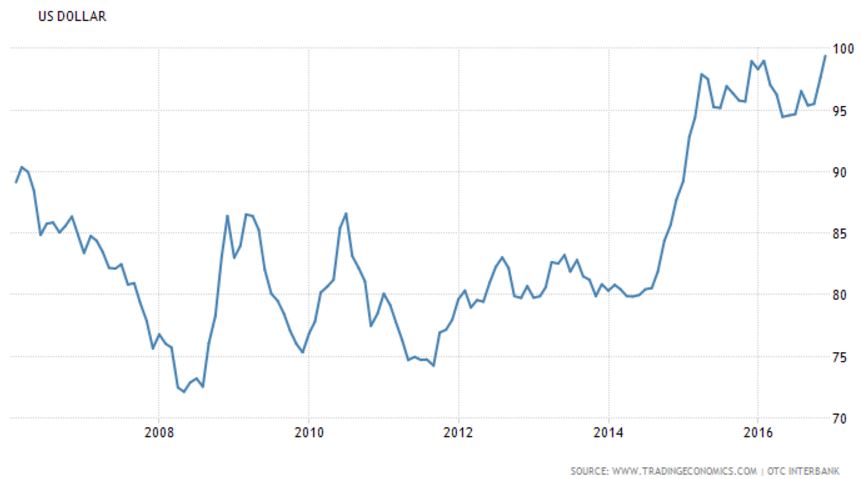
While the ten year chart gives a sense of perspective of these moves (the Dollar has reache 13 year highs, harking back to a time just before Greenspan really lost the plot and began the current trend in Ultra-Bubbles):
Source: TradingEconomics.com Click/Tap to Enlarge
Hence behind the smooth running of the artificial market in US equities some underlying trends seemed to accelerate and look in danger of picking up some negative momentum on the 23rd before calming down.
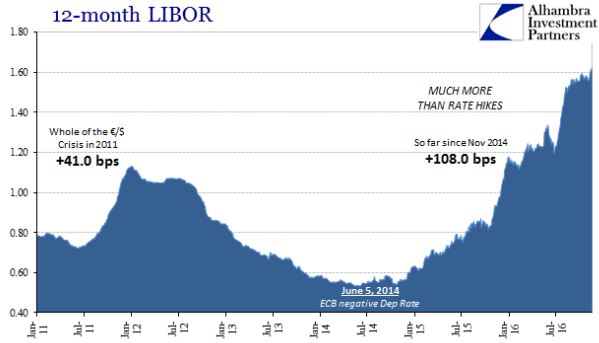
However calm being restored on this one unusual day does not change the underlying dollar shortage worries we have been discussing in recent weeks, which is perhaps highlighted by the latest spike in Honk Kong Overnight Bank Rates, which is worthy of some concern as globally funding stress is increasing as dollar shortages for global finance (which remains dollar based) get worse:

Source: ZeroHedge Click/Tap to Enlarge
Looking at 12 month dollar LIBOR sheds further light on the problem:
Source: Alhambra Investment Partners Click/Tap to Enlarge
You could argue the Fed with its potential 0.25% move is looking increasingly irrelevant.
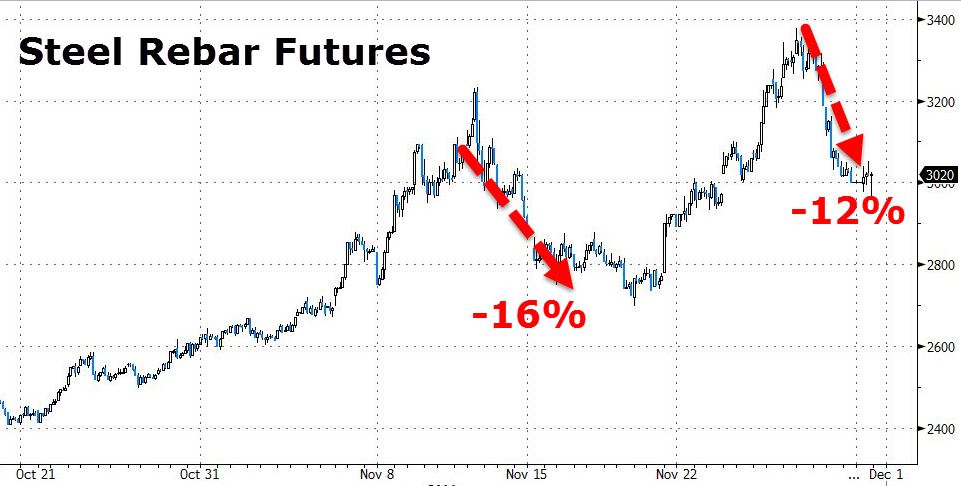
In the meantime recent months have seen the commodities insanity take of in China again (because we really need more worries right now), as it did earlier in the year (you may recall daily trading volumes in the Steel Futures markets early in the year exceeded global annual consumption of actual steel), however this has suddenly started to reverse:
Source: ZeroHedge Click/Tap to Enlarge
As have other commodity markets that globally have generally rallied on the unhinged “Trump is good” lunacy, which has disconnected logical thinking (actually make that just thinking!) totally from some asset markets, before maybe now taking heed, as the Chinese Zinc market perhaps shows.

Source: ZeroHedge Click/Tap to Enlarge
Can all this really tell us anything? Well combined with generally insane pricing, based upon hopes dreams and false narratives (discussed extensively, but of course around BREXIT HERE) perhaps only that beneath the surface real price discovery may be trying to emerge, although it may yet be eaten lurking Central Banks.
Time will tell but with the coming weekend carrying the potential Right, Left jabs of the Austrian Presidential election and the Italian Referendum who really knows?