
Good news! No nothing to do with the Dacia Sandero, but it’s UK GDP back to pre-crisis levels. Hurrah!
To be honest Prometheus suspects on some levels GDP has been above 2008 levels for a while ..in large part due to inflation and how GDP is calculated. But that diverts from the news of the moment so lets forget that.
So to reiterate: Hurrah!
With headline growth over the quarter of 0.8%, building on a similar figure in the first quarter the UK now looks to have the most robust growth among developed economies, with the IMF predicting 3.2% for the year….mmmm let me see, 0.8 + 0.8 =1.6, yep extrapolate that out over the next two quarters you get a total of 3.2%. Way to go IMF, on trying to prove to the world that economists are as prone to extrapolation bias as cows waiting to be milked; although to be fair cows have a better hit rate than most economists. (BTW I appreciate that 0.8% growth over 4 quarters compounds closer to 3.24% annualised but there’s dull commentary and then there’s catatonic)
As you might expect, given the UKs track record the core growth has come from the service sector, although the following Office of National Statistics (ONS) chart shows how stark our reliance has become on not making things:

(Source: UK ONS) Click/Tap to enlarge
You can see how clearly services dominate, although the pick up in production is more significant than it appears simply because it is a smaller constituent of the total. Perhaps a genuine surprise is the slump in construction, when you would have thought from both commercial and residential property markets builders would be throwing things up like mad; but apparently not. It is worth noting however that these figures are revised regularly and construction can be hard to pin down so don’t be surprised if the figure is revised up in future.
A more striking chart however is the one that shows how each sector is doing relative to the beginning of 2008 and that tells a very stark story:
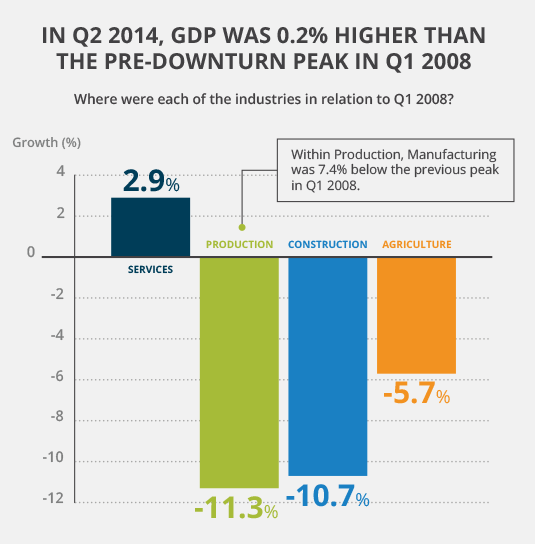
(Source: UK ONS) Click/Tap to enlarge
So there we have it, the services sector is only up 2.9%, but that is enough to compensate for significant falls across the rest of the economy. Bearing in mind it has been the goal of successive government to build up manufacturing these figures demonstrate the abject failure in this regards. I have to say I do wonder how the figures are calculated, for indeed we have an industrial sector denuded by the 1980s, yet we remain global leaders in value added engineering, while massive production of Japanese branded cars makes us a leading automotive manufacturing nation. Perhaps with so much of our production capacity owned overseas this doesn’t count for much, or is it that actually we aren’t doing too badly in manufacturing, it is just we do phenomenally well at services.
That’s a different take on the economy: our lopsided GDP is down largely to success, not to failure, with manufacturing sectors suffering all across Europe (ex Germany), while our world beating service sectors shrugs off the worst the cycle can throw at it! Looking across the channel at the plight of our European cousins that might be part of the story.
Of most concern from the economic standpoint is that the recovery is so dependent on service industry, which has a significant focus on the consumer who faces the odd headwind. Well more than the odd headwind, issues such as the weak state of income growth, the fall in the savings rate and the strong growth in house prices (generally a BAD thing…) driving property further away from the reach of the indebted young, all increasing the imbalances in the fundamental structure of the economy.
Ultimately it means that the recovery is built on weak foundations, with the imbalances that took us in to crisis in 2008 largely still in place (some are better, some much worse), while our biggest trading partner, the Eurozone, looks to be slipping backwards again.
Will any of this drive markets much. Probably not. With volumes low, summer sun here and investors confused by the mixed signals everyone will look to the US for guidance. Hence it is next weeks GDP figures which will show whether the US has rebounded from a shockingly weak Q1 figure, or if there is systemic weakness that cannot be blamed on the weather. This and a granular analysis of US corporate earnings (forget the CNBC bullish headlines about bottom line earnings beats, what is the top line doing? Where are the sales? Where is the cashflow? That’s what we want to know) will set the tone for markets for the rest of the year….or month anyway.
So as it won’t make much difference to markets I would suggest we enjoy the moment in the sun and look forward to a pleasent summer evening and a cool glass of our favourite.