
Markets globally regained composure following the volatile and worrying start to the year, breathlessly awaiting the co-ordinated action, or at least statement of intent from the G20 summit at the end of February. Surely the market thought TPTB (The Powers That Be) would work together to reinvigorate the global recovery. When literally nothing more than complacency was on offer did the markets swoon, fall, collapse even?
Nope, none of that rationality here I’m afraid, indeed the very fact that valuations remain dangerously high (discussed recently HERE) has not even crossed most commentators lips in what looks rationally like a surreal Bull Trap
No momentum in fact continued, with even Crude Oil managing to hold onto its 20%+ rebound with expectant eyes turning instead to the Chinese congress during the first weekend in March. Surely China must stimulate even more than it did (to little apparent effect) last year, it must find a way of transforming an economy from manufacturing to consumption over 12 months, not over 20 years, it must stimulate a massively over valued stock market, it must stimulate housing further to create nationwide double digit price to income ratios…..it must…it must….it must……………..IT DIDN’T
I mean it really didn’t do anything but massage growth expectations lower still, naturally leaving them still somewhat higher than anything resembling the likely actuality.
Indeed not only were no new massive stimulus plans announced but we have seen the latest figures indicating the draw on Chinese foreign reserves grow ever more alarming while capital flight last year has been estimated to be around $1tn.
Despite this though markets have remained close to recent highs, slipping only slightly while some commodities, particularly iron ore and steel have remained strong on hopes of a reinvigorated building boom (supported by notions of arithmetic that are clearly risible).
Does this tell investors all is right with the world? That the sell off was misguided panic? That the market became a true bargain and a massive buying opportunity…….Errrrr……No way to put this politely…..No, not even slightly, on any level.
No none of these notions is even vaguely near the mark, or even in the right ball-park, however while the initial days of the rally bore all the hallmarks of a short squeeze, as the assets that had been sold down the most rebounded the most, almost certainly as shorts banked a profit before month end, while longs drank greedily from the trough trying to drive their positions back up. Now however there seems to be a mood of deliberate myopia, wishing away the data coming down the pipes in the hopes that Super Mario will give them reason for joy when he speaks, a week later than usual on Thursday.
Now the core problem with this notion is that even if Mario does unleash fresh stimulus its efficacy is bound to be limited, with increasing realisation (of the obvious) that negative interest rates may be a bad thing (they are) and maybe its time to stop pushing policies that have failed (it is). As we have discussed before the credit channels have not suddenly opened up within Europe as a result of all the funny money sloshing around and the real positive impact so far has been limited largely to crushing the Euro.
The really frustrating thing with all this expectancy is that Mario himself said in 2014 that monetary policy can only go so far, making it clear that fiscal stimulation is key, while the freshly revealed (always evident) weakness in many Euro-bank balance sheets supports the notion we discussed back in 2014 (HERE) that until bad debts can be packaged up and monetised, TARP style, then fundamentally weak balance sheets will remain a drag regardless of end loan demand.
Then there’s China, which the world has finally noticed is in a sticky situation. However on the basis a picture paints a thousand words lets look at some PMI’s which as ever are instructive.
First China:

Source: Markit Click/Tap to Enlarge
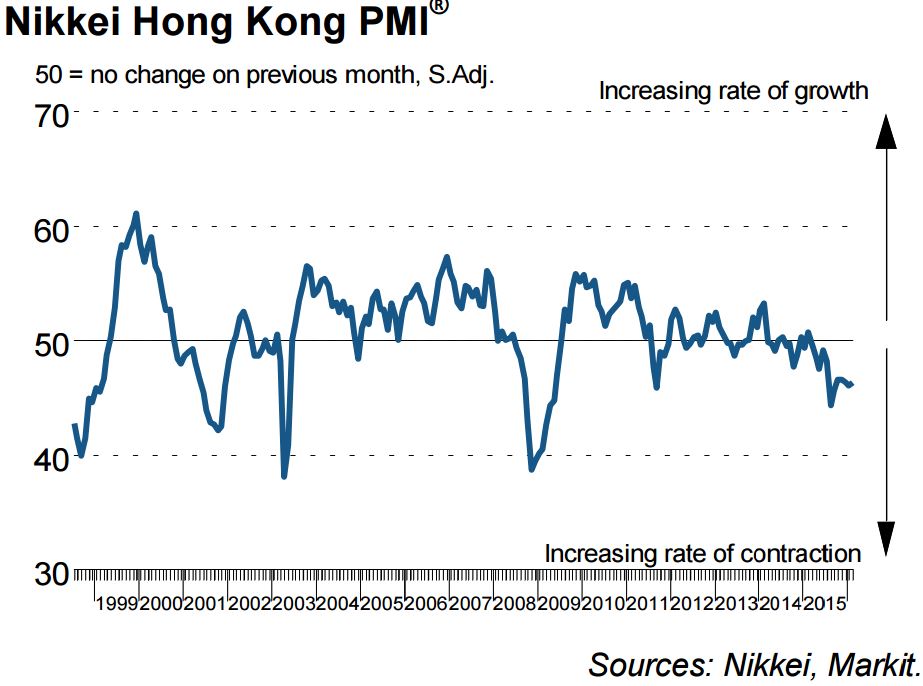
You can see that China has extended its run below the 50 break-even line for an extended period. More worryingly the much more service oriented Hong Kong is not happy either:
Source: Markit Click/Tap to Enlarge
Now the story is repeated across most of the rest of the EM and Asian space, although both Vietnam and India have both moved back into the positive plus 50 territory, important as they remain the lower cost producers of last resort.
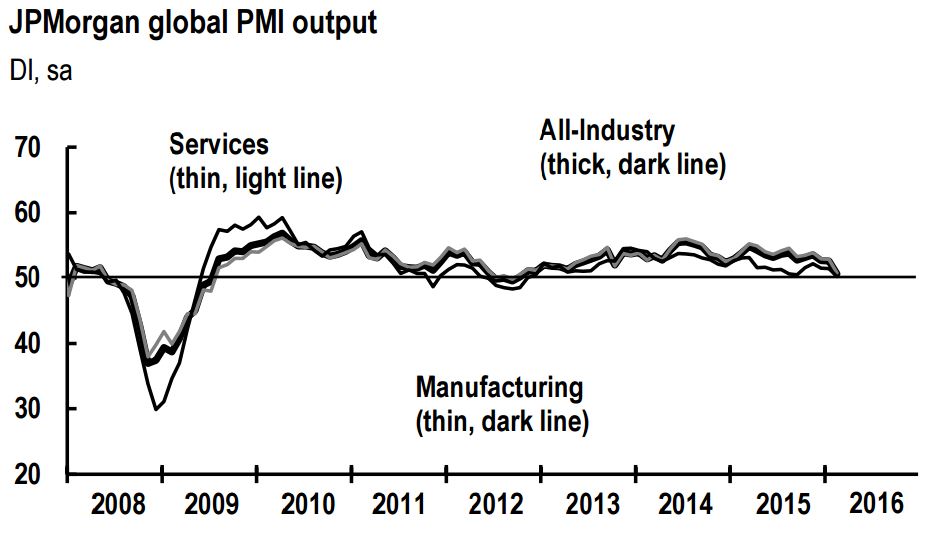
This general malaise is reflected in a global PMI that looks troubling:
Source: Markit Click.Tap to Enlarge
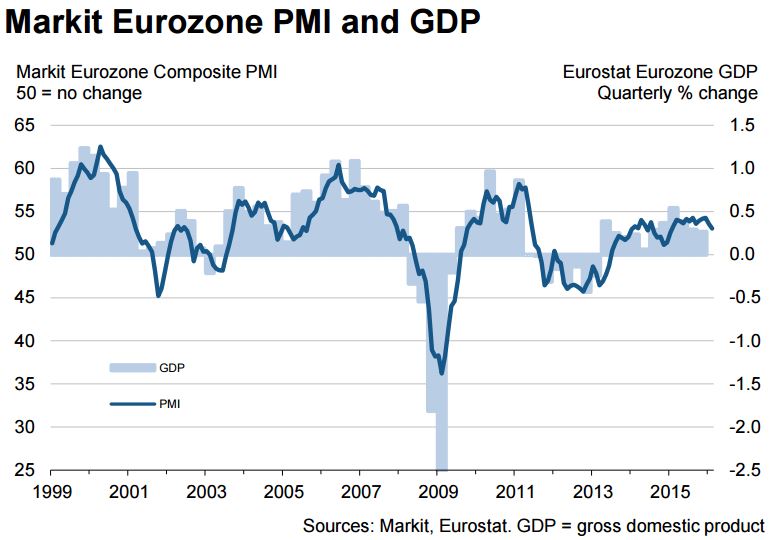
The story is less than stellar in the Eurozone, particularly bearing in mind the alleged stimulus that has been thrown down onto the economy, although at least it remains positive:
Source: Markit Click/Tap to Enlarge
We can see historically that GDP has a close correlation to the PMI over time so the latest softening is not a solid vindication of Draghi’s policies.
Looking to UK output however at least we can see the numbers remain slightly positive:

Source: Markit Click/Tap to Enlarge
Interestingly this Manufacturing PMI remains above the 50 break-even line but the historical ONS data it is compared to, rather than showing a break-even at 50, actually requires 54 to post a positive number, at least historically. This perhaps tells us to be both cautious at current levels yet pleased that UK managers tend to the optimistic. The picture is similar in the US:

Source: Markit Click/Tap to Enlarge
Again the real break-even line appears to be above 50 and again the PMI has slipped below this level. Time will tell how this evolves but there is nothing in this, and a swathe of other data we will present over coming days to think either the global economy or global markets are fixed.